Every day, businesses need capital.
They need money for equipment, inventory, payroll, expansion, acquisitions, commercial real estate, marketing, working capital, and countless other business needs.
Billions of dollars move through the commercial finance industry serving those businesses.
But there is another side of the transaction that many professionals never think about:
Follow the Transaction
Someone is getting paid for helping connect those businesses with the capital and financial solutions they need.
If you already work with business owners, the bigger question may be: Why isn't that someone you?
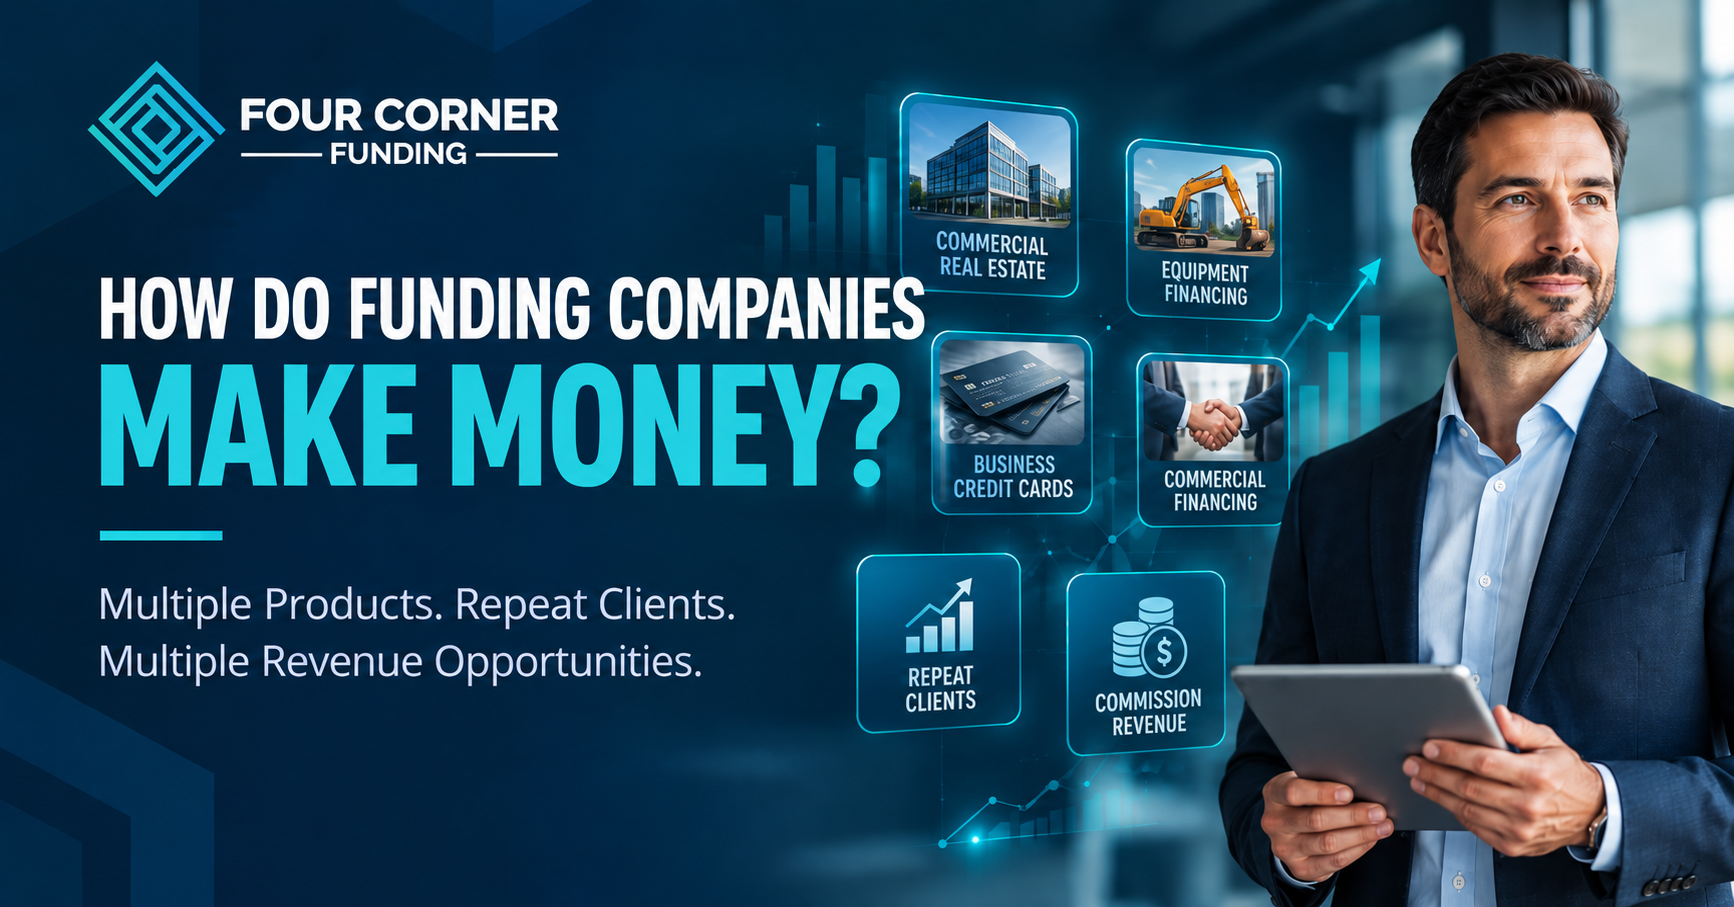
Business Funding Is More Than One Product
One of the biggest advantages of the commercial finance industry is the number of potential solutions a business owner may need throughout the life of the company.
Those needs may include:
✓ Working Capital ✓ Business Lines of Credit ✓ SBA Financing ✓ Equipment Financing ✓ Receivables Financing | ✓ Commercial Real Estate ✓ Acquisition Financing ✓ Revenue-Based Financing ✓ Business Credit Cards ✓ Business Credit Building |
That means a business funding relationship does not necessarily begin and end with one transaction.
Revenue Stream #1: Commercial Funding Transactions
Commercial financing is one of the primary ways funding professionals generate revenue.
When an eligible transaction closes, compensation may be paid according to the lender, funding source, product, transaction structure, and executed partner agreement.
The size of commercial transactions can vary dramatically.
Think About the Size of the Opportunity
A small business may need $50,000 in working capital.
A growing company may need $250,000 for equipment.
A business acquisition may require $750,000.
A commercial real estate transaction may involve $1 million or considerably more.
The partner's compensation depends on the specific transaction and agreement, but the fundamental business model is straightforward:
Help businesses access capital.
Participate in eligible transaction revenue.
Participate in eligible transaction revenue.
Revenue Stream #2: Business Credit Card Stacking
Business credit card stacking can create another significant revenue opportunity for companies serving qualified business owners with strong personal and business credit profiles.
In a stacking engagement, a funding professional may help the client pursue multiple business credit card approvals in a strategically sequenced application process.
The service fee is established by the company providing the service, subject to applicable agreements and legal requirements.
Illustrative Example
$100,000 in approved business credit
If a funding company charges a 10% service fee:
$10,000 Gross Service Fee
The example above is for illustration only. Approval amounts, pricing, compensation, client eligibility, and results vary. No specific revenue or approval amount is guaranteed.
Revenue Stream #3: Business Credit Building
Not every business is ready for substantial financing today.
Some businesses need to establish or strengthen their business credit profile before pursuing larger capital opportunities.
That creates another potential service relationship.
Today's Credit-Building Client May Become Tomorrow's Funding Client.
By helping a business establish a stronger financial foundation, the relationship may continue as the company becomes eligible for additional funding products in the future.
Revenue Stream #4: The Same Client Can Come Back Again
This is where the commercial funding model becomes particularly interesting.
Businesses don't stop needing capital after their first financing transaction.
Their needs change as the company grows.
One Client Relationship Could Look Like This
Stage 1: Establish business credit
Stage 2: Access business credit cards
Stage 3: Obtain working capital
Stage 4: Finance new equipment
Stage 5: Purchase commercial property
Stage 6: Finance an acquisition or expansion
Not every client will follow that exact path, but it demonstrates why the lifetime value of a business relationship can be significantly more important than a single transaction.
Don't Just Chase Transactions. Build Relationships.
The client you help today may create additional opportunities for years to come.
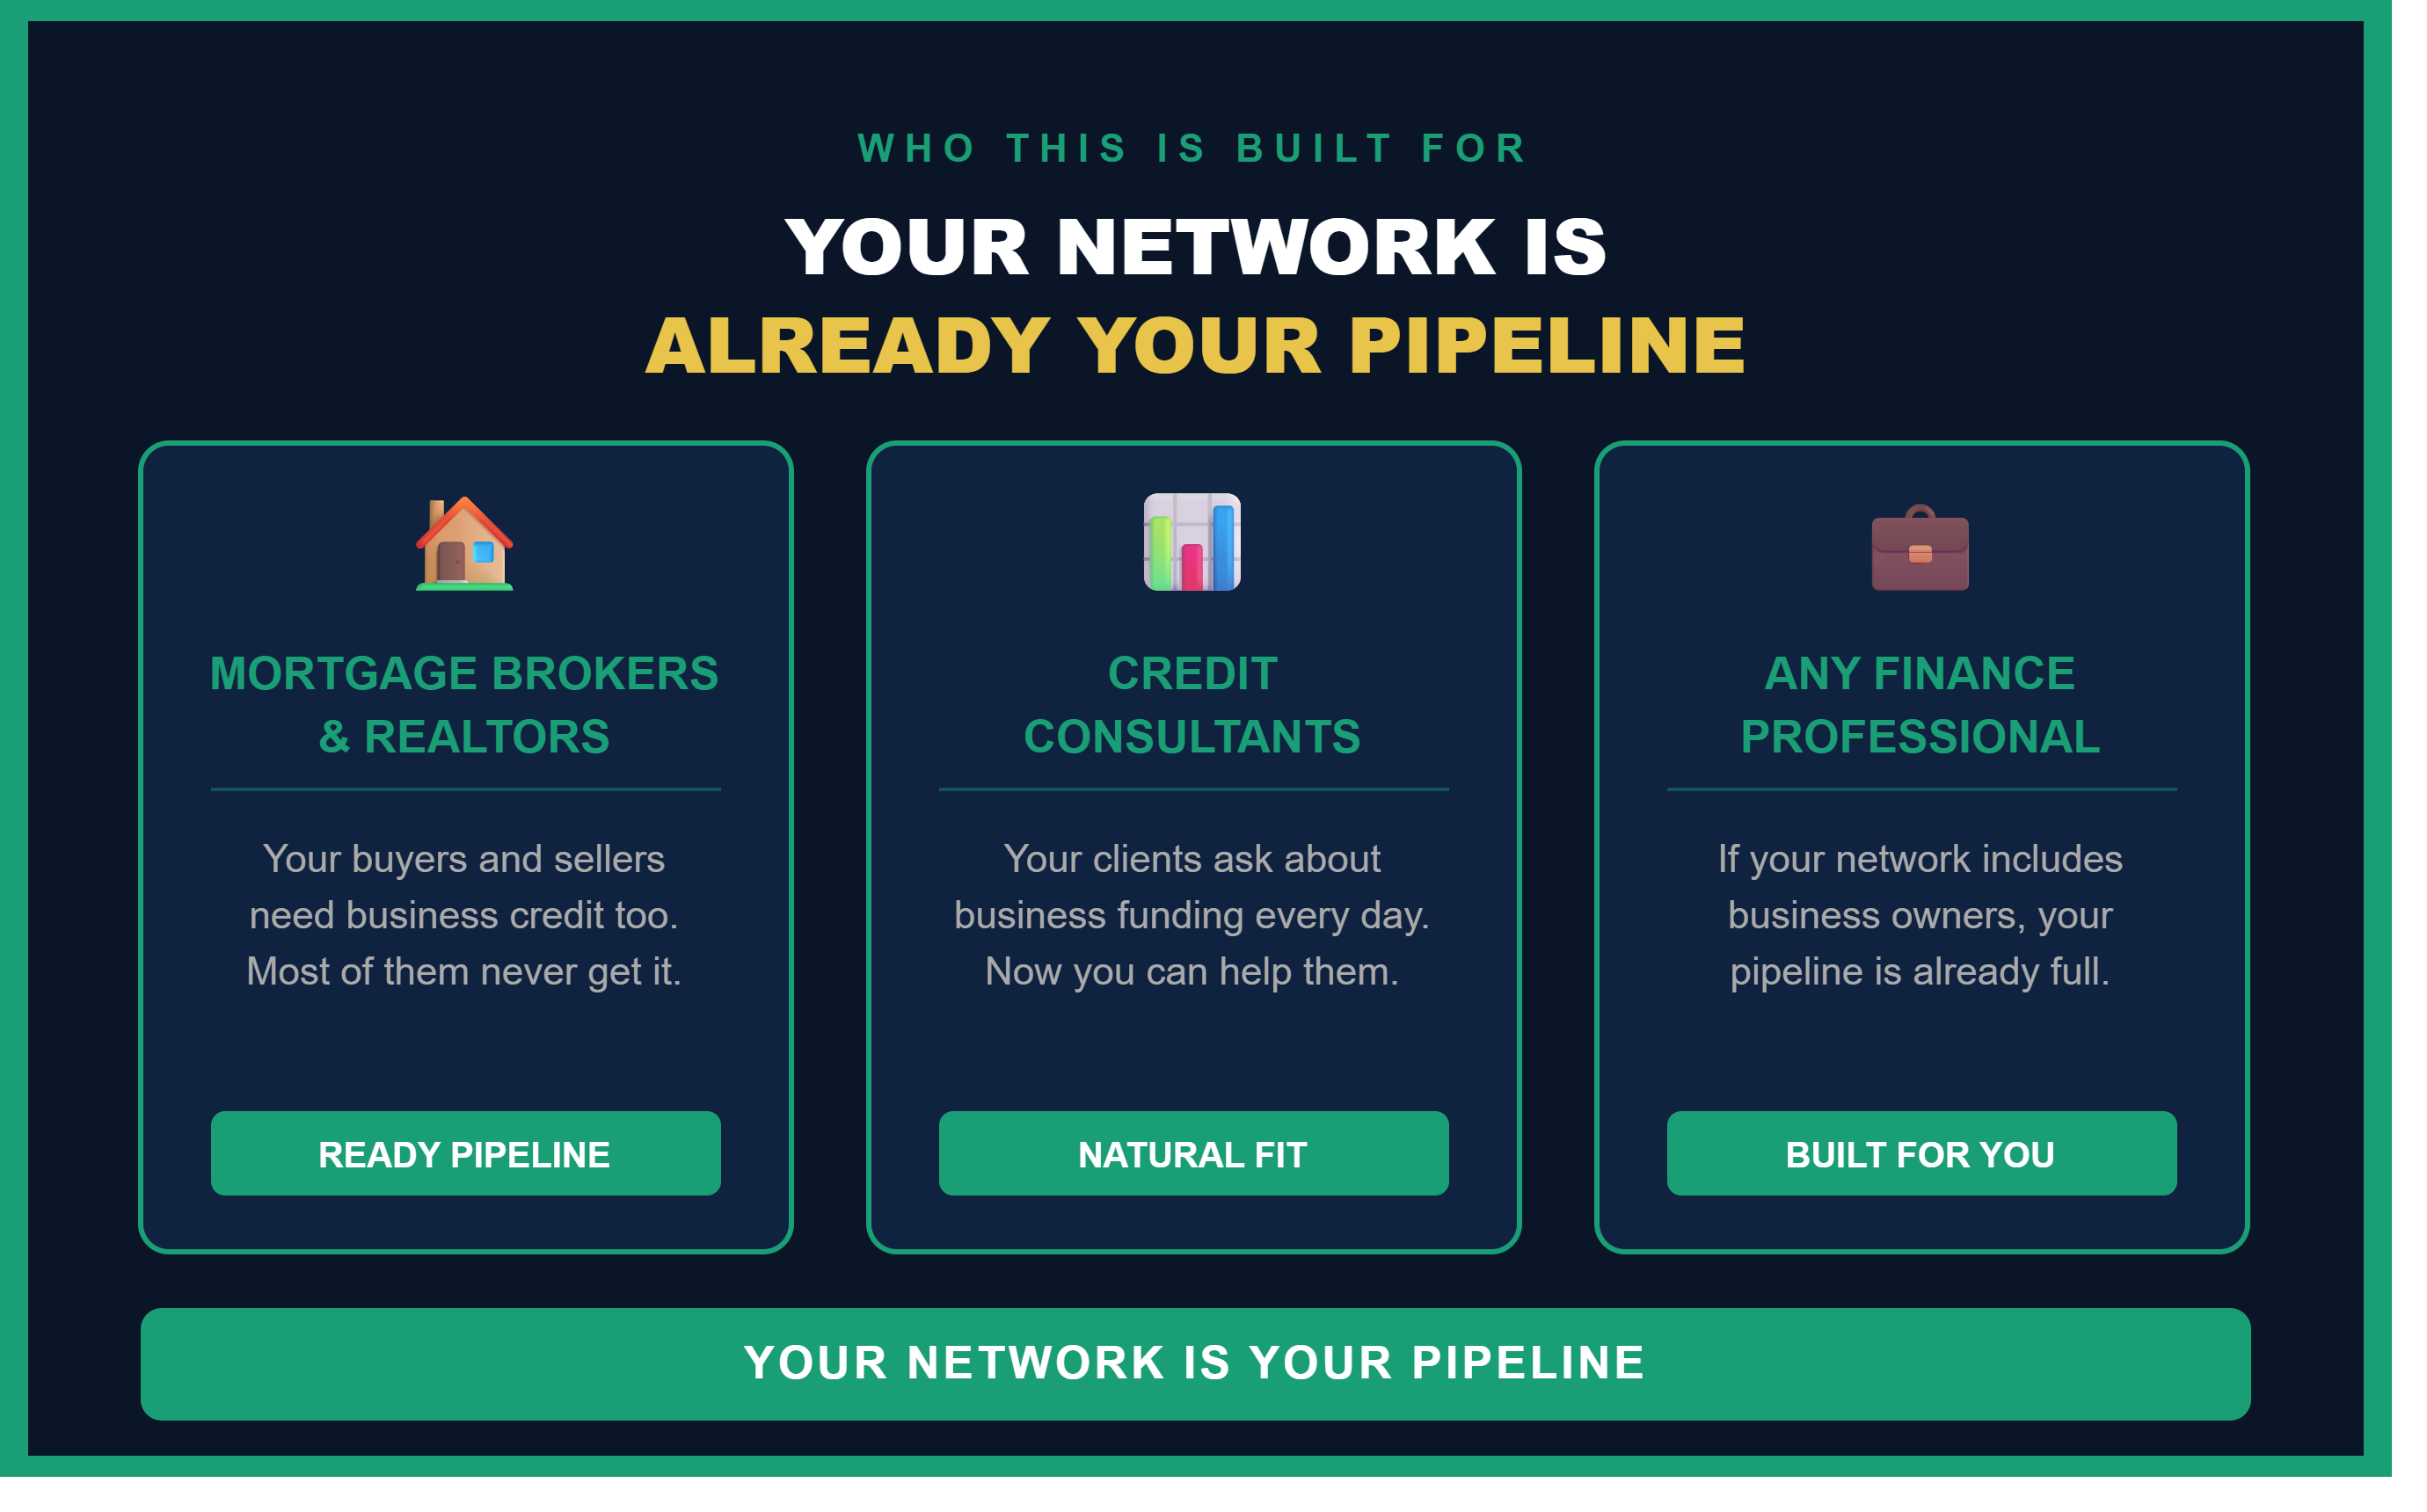
What If You Already Have Business Clients?
This model can be especially interesting for professionals who already serve business owners.
| ✓ CPAs & Tax Professionals | ✓ Business Consultants |
| ✓ Credit Professionals | ✓ Business Coaches |
| ✓ Insurance Professionals | ✓ Business Brokers |
| ✓ Commercial Finance Professionals | ✓ Entrepreneurs |
If your clients already ask you questions about cash flow, credit, equipment, expansion, acquisitions, or financing, those conversations may represent opportunities you are currently referring away.
Referral Income vs. Building Your Own Funding Company
There is a major difference between occasionally referring a funding opportunity and building a business around commercial finance.
Referral Model
Send the client somewhere else.
Another company controls the brand, experience, relationship, and future transactions.
White Label Model
Build the relationship under your own brand.
Develop your own client base while using technology and infrastructure designed to support the funding process.
The Infrastructure Behind the Revenue
Making money in commercial finance is not simply about finding someone who needs a loan.
A scalable funding company needs systems capable of managing the entire relationship.
That includes:
- Lead and client management
- Funding applications
- Document collection
- Funding readiness evaluation
- Business credit tools
- Capital-access workflows
- Lender and funding-source relationships
- Transaction management
- Commission tracking
- Ongoing client management
That's the infrastructure Four Corner Holdings has spent years developing.
The Bigger Opportunity
Don't just earn from a funding transaction.
Build a funding company.
Own Your Own Funding Company™
The Four Corner Funding White Label Partner Program was designed for professionals and entrepreneurs who want more than a referral relationship.
It provides the opportunity to build a branded business around funding, business credit, capital access, and long-term client relationships without spending years developing the underlying technology and infrastructure from scratch.
Your Brand. Your Clients. Your Platform.
Four Corner Funding White Label Partner Program
Ready to Build Your Own Revenue Stream?
Explore the platform, see how the White Label Partner model works, and discover how commercial funding could become part of your business.
EXPLORE THE WHITE LABEL PLATFORM
Own Your Own Funding Company™
ACCESS CHANGES EVERYTHING™
Four Corner Funding is not a lender. Financing products are provided by third-party funding sources and are subject to underwriting, eligibility requirements, lender guidelines, and approval. White Label Partner compensation, pricing, revenue sharing, and program terms are governed by the applicable executed partner agreement and may vary by product or transaction. Examples are illustrative only. No specific financing, approval, commission, or income results are guaranteed.