If you are a mortgage loan officer, Realtor, mortgage broker, or other real-estate professional, you already understand something most business owners never have to think about:
Your income can be heavily influenced by an industry cycle you do not control.
Interest rates move. Purchase volume changes. Refinances disappear and return. Buyers hesitate. Inventory changes. Transactions take longer to close.
But your professional relationships do not suddenly disappear when residential mortgage activity slows.
The Bigger Question
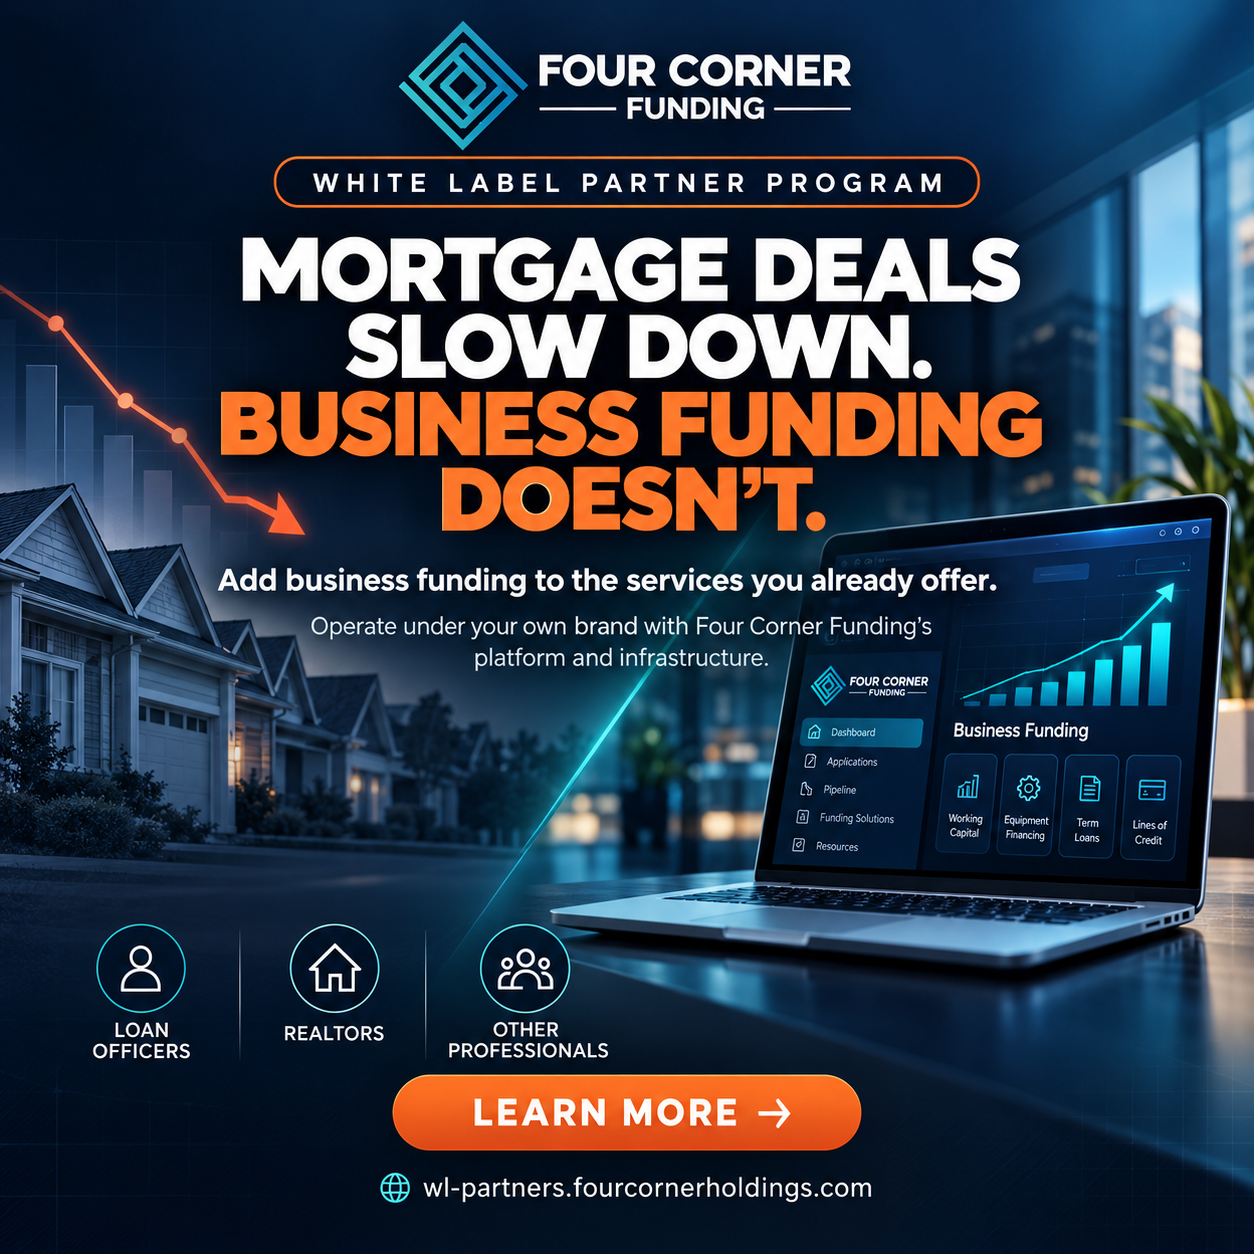
What if your mortgage or real-estate business could offer another financial service when residential transactions slow down?
Business owners still need working capital, equipment, lines of credit, acquisitions, commercial real estate financing, business credit, and other forms of capital.
This Week's Mortgage Numbers Tell the Story
The latest industry data provide a clear example of how quickly the residential mortgage environment can shift.
For the week ending September 25, 2026, Mortgage Bankers Association data showed the average contract rate on a conforming 30-year fixed mortgage reaching 7.30%.
During the same week:
📉 Total mortgage applications fell 6%
📉 Purchase applications fell 4%
📉 Purchase applications were 14% below a year earlier
📉 Refinance applications fell 9%
📉 Refinance activity was 56% below a year earlier
For mortgage professionals, none of this means the industry is disappearing.
It means the residential mortgage business is cyclical.
Your primary industry may be cyclical.
Your client relationships do not have to be.
Your client relationships do not have to be.
The Commercial Side of Finance Is a Very Different Market
While residential professionals are dealing with elevated rates and lower mortgage application volume, commercial capital markets continue to represent an enormous financial ecosystem.
The Mortgage Bankers Association reported this week that total commercial and multifamily mortgage debt outstanding reached a record $5.1 trillion at the end of the second quarter of 2026.
That was an increase of $42.9 billion during the quarter.
MBA also reported that commercial and multifamily mortgage loan originations during the second quarter were 16% higher than a year earlier.
What does that mean for a mortgage professional?
It means residential mortgages are only one part of the broader capital marketplace. The businesses already around you may have financing needs that have nothing to do with purchasing or refinancing a home.
Businesses Continue to Need Capital
A business owner does not stop needing capital because residential mortgage rates moved higher.
Companies still need money to hire employees, purchase inventory, expand locations, buy equipment, manage receivables, execute contracts, acquire competitors, purchase commercial property, and strengthen cash flow.
Depending on the business and transaction, those needs can include:
| Working Capital | Business Lines of Credit |
| Equipment Financing | SBA Financing |
| Commercial Real Estate | Acquisition Financing |
| Receivables Financing | Business Credit |
You Do Not Have to Leave the Mortgage or Real-Estate Industry
This is the important part.
Adding business funding does not mean abandoning the business you already built.
It means adding another service line to it.
You already have relationships.
You already understand financing conversations.
You already know how to gather documents, communicate with clients, manage transactions, explain financing terms, and follow a deal through to closing.
Many of your clients, referral partners, Realtors, investors, contractors, developers, landlords, and local business owners may also own businesses.
Do Not Replace Your Existing Business.
Expand What It Can Offer.
Expand What It Can Offer.
Add business credit and commercial finance to the services you already provide.
What Is the Four Corner Funding White Label Partner Program?
Four Corner Holdings developed the White Label Partner Program for professionals who want to offer business funding and business-credit services under their own brand without having to build the underlying technology and operational infrastructure from scratch.
This is substantially different from simply receiving a referral link.
The objective is to help you build the service into your own business.
White Label Partner
Your Brand. Your Clients. Your Platform.
Four Corner provides the technology and infrastructure behind the experience while you build the client relationship and your own business.
What Do You Actually Get?
The program is designed to provide much more than access to financing products.
Depending on platform configuration and available features, the White Label ecosystem can include:
- Your own branded client experience
- Lead and client CRM
- Funding applications
- Pre-Qualification and Funding Readiness
- Underwriting and prequalification infrastructure
- Capital Access tools
- Business Credit Builder
- Business Credit Card Sequencing strategies
- Document management
- Funding workflows
- Funding-source routing and matching infrastructure
- Pipeline and transaction tracking
- Commission tracking
- Embeddable client applications
- Training through Four Corner Academy
- Ongoing platform and operational support
This Can Create an Additional Revenue Channel
For mortgage professionals and Realtors, one of the most compelling reasons to add commercial finance is diversification.
Your income does not have to depend exclusively on how many residential purchases or refinances close this month.
White Label Partners may have revenue opportunities through eligible commercial funding transactions, Business Credit Builder services, Business Credit Card Stacking services, and repeat client relationships, subject to the applicable partner agreement and transaction.
Think Beyond One Closing
A client might need working capital today.
Equipment financing next year.
A commercial property later.
And acquisition or expansion capital as the business grows.
Not every client follows the same path, but commercial finance can create a longer-term financial relationship rather than a single transaction.
Realtors May Be Sitting on the Same Opportunity
Realtors often have relationships with investors, contractors, landlords, property managers, builders, entrepreneurs, and small-business owners.
Those clients may need much more than residential property financing.
They may need equipment.
They may need capital to renovate a property.
They may need commercial real estate financing.
They may need working capital for the company that generates the income behind their next transaction.
Adding business funding capabilities can allow the Realtor or real-estate professional to become more valuable to the same network they have already spent years building.
You Do Not Have to Build the Infrastructure Yourself
Building a commercial finance company independently requires far more than finding a few lenders.
It can involve software, CRM systems, client portals, applications, document management, underwriting processes, funding workflows, funding-source relationships, business-credit systems, transaction tracking, training, compliance processes, billing, commissions, and ongoing software development.
Four Corner Holdings has invested years and more than $1.7 million developing the technology and infrastructure behind the platform.
The point is not simply how much was invested.
The point is that a White Label Partner does not need to reproduce all of it before adding these services.
Keep Doing What You Already Do.
Continue originating mortgages. Continue selling real estate. Continue serving your existing market. The White Label Partner model simply gives you another capability to offer when the client's need falls outside the residential transaction.
Own Your Own Funding Company™
You already built the relationships.
You already learned how to sell and close financial transactions.
You already understand how important responsiveness, documentation, trust, and follow-up are.
The question is whether those capabilities should only generate revenue when somebody is buying or refinancing a home.
Your mortgage or real-estate business does not have to disappear when the market slows. It can expand.
Four Corner Funding White Label Partner Program
Add Business Funding to the Business You Already Have.
See how mortgage professionals, Realtors, consultants, credit professionals, and other business-service professionals can build commercial finance into their existing business under their own brand.
EXPLORE THE WHITE LABEL PARTNER PROGRAM
Your Brand. Your Clients. Your Platform.
ACCESS CHANGES EVERYTHING™
Market data: Residential mortgage application and rate figures referenced above are based on Mortgage Bankers Association weekly survey data reported September 30, 2026. Commercial/multifamily debt figures are from MBA's September 29, 2026 Commercial/Multifamily Mortgage Debt Outstanding report. Q2 origination growth is from MBA's August 6, 2026 quarterly originations report.
Four Corner Funding is not a lender. Financing products are provided by independent third-party funding sources and are subject to underwriting, eligibility requirements, lender guidelines, documentation verification, geographic restrictions, and final approval. White Label Partner compensation, pricing, revenue sharing, and program terms are governed by the applicable executed partner agreement and may vary by product or transaction. No specific financing, approval, commission, income, or business result is guaranteed. Professionals in regulated industries should confirm that any additional services they offer are consistent with applicable licensing, professional, employer, brokerage, and regulatory requirements.