Introduction
Most business owners assume funding is based on one factor—usually credit score.
From an underwriting perspective, that assumption is incorrect.
Business funding approvals are based on a combination of factors including credit, revenue, structure, and risk exposure. When one or more of these areas are weak or misaligned, applications are declined.
Understanding why applications get declined is the first step to improving approval outcomes.
The Reality Behind Funding Declines
Declines are not random.
They are the result of:
- Risk misalignment
- Incomplete business profiles
- Weak financial indicators
- Applying at the wrong time
In most cases, the business could have qualified—but applied before it was ready.
Top Reasons Business Funding Applications Get Declined
1. Lack of Pre-Qualification
The most common issue is skipping pre-qualification.
Applying without understanding eligibility leads to:
- Submitting to the wrong funding products
- Failing basic underwriting criteria
- Immediate declines
Pre-qualification exists to prevent this.
2. Weak or Incomplete Business Credit Profile
Many businesses:
- Have no established business credit
- Have too few tradelines
- Have inconsistent reporting
Without a verifiable credit profile, underwriting has limited data to assess risk.
3. Inconsistent or Insufficient Revenue
Revenue is a core underwriting factor.
Common issues include:
- Low monthly revenue
- Irregular deposits
- Negative cash flow patterns
Even strong credit cannot offset weak or unstable revenue.
4. Poor Business Structure (Fundability Issues)
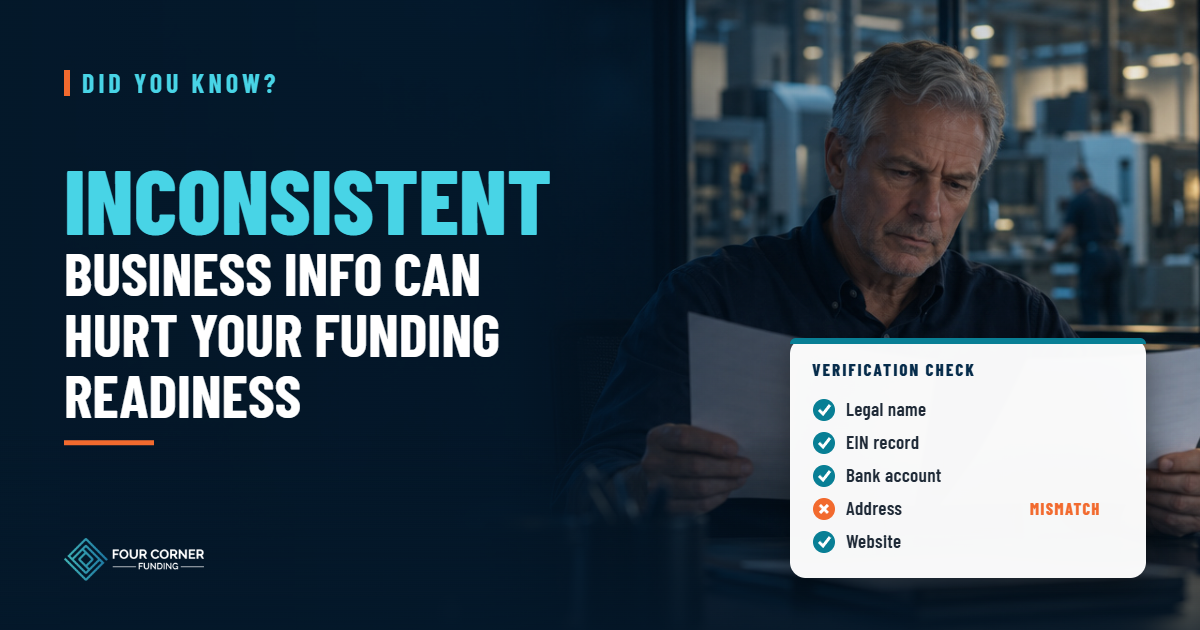
Businesses often fail basic verification checks due to:
- Mismatched business information
- No professional business presence
- Inconsistent records across databases
These are not cosmetic issues—they directly impact approval decisions.
5. High Existing Debt or Payment Burden
Underwriting evaluates current obligations.
If a business already has:
- High monthly payments
- Multiple active obligations
- Stacking risk
…it may be declined due to overexposure.
6. Applying for the Wrong Type of Funding
Not all funding is appropriate for every business.
Common mistakes:
- Startups applying for products requiring time in business
- Low-revenue businesses applying for high-limit financing
- Businesses applying without meeting minimum thresholds
This results in automatic disqualification.
What Underwriting Is Actually Evaluating
Every application is reviewed based on:
- Credit profile (personal and/or business)
- Revenue consistency
- Time in business
- Banking activity
- Industry risk
- Existing obligations
- Business verification
Approval is based on overall risk—not a single metric.
How to Avoid Getting Declined
The solution is not applying more—it’s applying correctly.
Focus on:
- Establishing a complete business profile
- Building business credit strategically
- Maintaining consistent revenue and deposits
- Reducing unnecessary debt exposure
- Completing a proper pre-qualification review
Why Timing Matters More Than Urgency
Most declines happen because businesses apply too early.
Funding should be approached as a structured process:
- Establish foundation
- Build credit profile
- Verify eligibility
- Apply strategically
Skipping steps leads to denials.
Start With Pre-Qualification (CTA)
Before submitting any funding application, the first step should be determining where your business stands.
A structured pre-qualification review evaluates:
- Credit position
- Revenue and banking
- Business structure
- Funding readiness
From there, you can identify:
- Whether you qualify now
- What options are realistic
- What needs to be improved
👉 Start here: https://fourcornerfunding.com/pre-qualification
Conclusion
Most funding declines are preventable.
They occur when businesses apply without understanding underwriting requirements or without being fully prepared.
By focusing on structure, eligibility, and timing, businesses can significantly improve their approval outcomes and avoid unnecessary denials.