Ask almost any commercial lender whether they need more submissions, and the honest answer is usually no. The inbox is not empty. The problem is what is in it.
Files arrive incomplete. Business records do not match from one document to the next. A borrower already carrying several obligations is presented as a clean first-position request. A working-capital need shows up as an equipment deal, or the other way around. Each of those files still has to be opened, read, questioned and declined, and every one of them consumes underwriting capacity that could have gone to a borrower who actually fits.
At Four Corner Funding, we built our origination process around a different question. Not how many files can we send? but which files belong in front of this lender at all?
The principle
Volume is easy to send. Fit is hard to build.
The Hidden Cost of Submission Volume
Much of the commercial origination market is built to reward activity. A borrower is collected, a package is assembled quickly, and the same file is sent to as many funding sources as possible in the hope that one says yes. For the originator, the cost of a poorly matched submission is close to zero. For the lender receiving it, the cost is real:
| What arrives | What it costs the lender |
| Incomplete or stale documentation | Back-and-forth requests before review can even begin |
| Inconsistent business identity and records | Verification time and avoidable questions |
| Undisclosed or understated existing obligations | Late-stage surprises after work has already been done |
| Requests outside the stated credit box | A decline that never needed to happen |
| The same file shopped to many sources at once | Competing for a borrower who was never prepared |
None of this is visible in a submission count. It shows up in turnaround times, pull-through rates and the hours an underwriting team spends on files that were never going to close.
Readiness Happens Before Submission, Not After
Four Corner Funding operates a commercial funding platform designed around readiness. Before a request is considered for any funding source, the business goes through a structured intake and internal review. Depending on the request, that work can include pre-qualification, a fundability review, business-identity and records consistency, documentation readiness, existing-obligation review and a use-of-funds match to the right financing category.
The point is simple: problems that can be found before submission should be found before submission. A lender should be evaluating credit, not chasing paperwork.
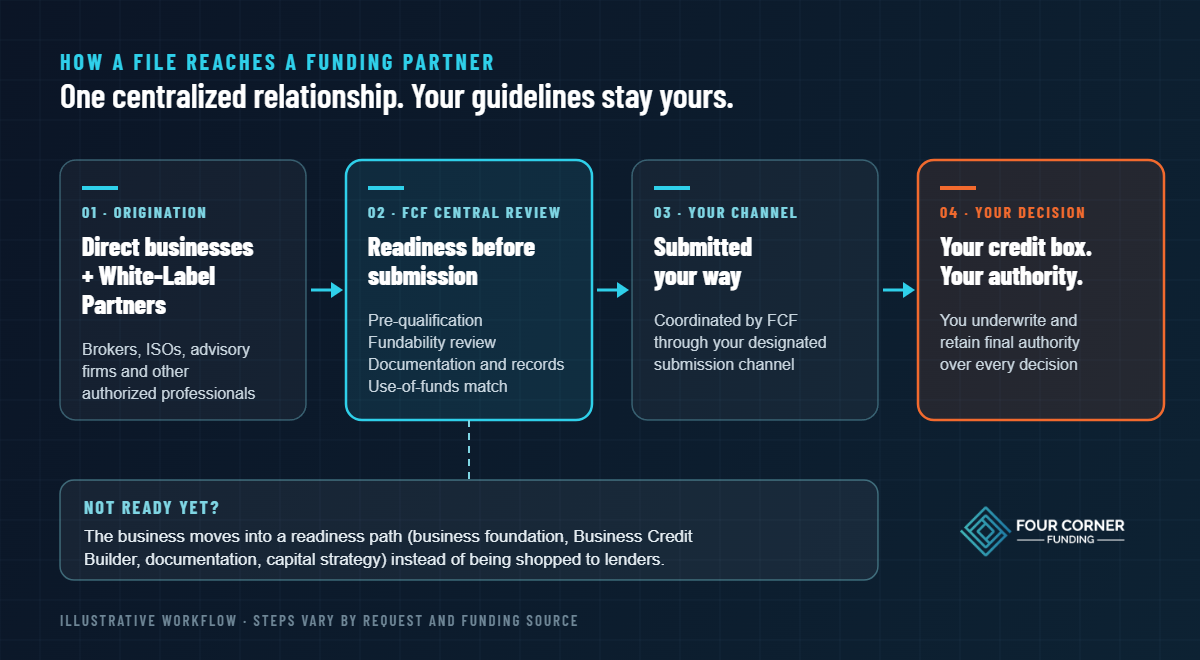
How a file reaches a funding partner. Illustrative workflow; steps vary by request and funding source.
One Relationship Instead of Hundreds
Our origination comes from two directions: businesses that come to Four Corner Funding directly, and a network of White-Label Partners. Those partners are qualified brokers, ISOs, advisory firms and other authorized professionals who originate and manage borrower relationships under their own brands on our platform.
What matters to a lender is what happens next. Every request, regardless of where it originated, flows to one place.
Four Corner Funding controls the lender side. Lender matching, submission, lender communication, follow-up and funding operations are handled centrally by our team, not by individual originators.
Your guidelines stay confidential. Originating partners do not receive lender identities, contacts, credit guidelines or funding relationships, and they do not communicate with funding sources through the system.
Submissions arrive your way. After internal review, files are coordinated through each funding source's designated submission channel and requirements.
Borrowers own their authorizations. Borrowers complete their own applications, disclosures and authorizations, so the file you receive comes from the business itself.
For a lender, that means a single accountable counterparty, consistent file packaging and one team to call, instead of dozens of independent originators each presenting deals in their own way.
A prepared file lets a credit team spend its time on the credit decision.
The Borrowers Who Aren't Ready Don't Disappear
In a volume-driven channel, a business that is not ready for financing is usually shopped anyway, or simply dropped. Neither outcome helps a lender.
On our platform, a business that does not yet fit a funding category moves into structured readiness work instead: strengthening its business foundation and records, developing its business credit profile through our Business Credit Builder, organizing documentation and building a capital strategy. Our public positioning to borrowers is direct: funding if you're ready, a path forward if you're not.
For funding partners, that produces something most origination channels cannot: a pipeline that matures. Some of the businesses that are not a fit this quarter are being prepared to become qualified borrowers later, with a documented history of how they got there.
For our funding partners
We would rather send you three files that fit than thirty that don't.
Credit Authority Stays With the Lender
Four Corner Funding is not a lender and does not make credit decisions. Our internal review is preparation and screening, not approval. Each funding source applies its own underwriting, sets its own criteria and retains final authority over every financing decision.
That division is deliberate. You define the box. We do the work that determines which files belong in it.
The Funding Categories We Work Across
Our borrower base spans small and mid-sized operating businesses with needs across the commercial spectrum, including:
| Working capital and lines of credit | Term and revenue-based financing |
| Equipment financing | Receivables financing |
| SBA financing through participating lenders | Acquisition financing |
| Commercial real estate | Construction financing |
Who We Want to Work With
We are selectively expanding our network of qualified direct funding institutions: banks, credit unions, commercial finance companies, specialty lenders and private credit providers. We are not looking to collect ISO agreements or build a list of names. We are looking for funding partners who:
- Lend directly and can describe a clear credit box
- Value prepared, well-matched files over raw volume
- Communicate decisions and conditions promptly
- Want a long-term origination relationship rather than one-off deals
See the Model for Yourself
We produced a short overview film for prospective funding partners. It walks through how borrowers are originated, reviewed and prepared on the platform, and how requests reach a funding source.
Watch the Institutional Origination & Funding Partnership Overview (7 min)
For direct lenders and commercial capital providers
Your underwriting guidelines. Our origination infrastructure. One centralized funding relationship.
If your institution is open to well-prepared commercial borrowers who fit your criteria, let's talk.
SCHEDULE AN INTRODUCTORY CALL LENDER PARTNERSHIPS
Or call (813) 391-3333
Important information
Four Corner Funding is a registered Florida fictitious name of Four Corner Holdings, LLC. Four Corner Funding is not a lender and does not make credit decisions. Financing is provided by independent funding sources, which apply their own underwriting and retain all credit decisions. Internal review, pre-qualification and readiness screening are not credit approvals. Workflow descriptions and graphics are illustrative; processes vary by request and funding source. This article is general information and is not an offer of, or commitment to, any commercial terms, volume or relationship. Any funding-source relationship is subject to mutual review and a written agreement.