Market data as reported through October 1, 2026. Each figure is dated to its source. Sources are listed at the end of this article.
Mortgage rates are back above 7%. Freddie Mac’s Primary Mortgage Market Survey, published October 1, 2026, put the average 30-year fixed rate at 7.28%, up from 7.03% a week earlier and 6.34% a year earlier. The 15-year fixed rate averaged 6.60%.
Application volume has fallen with it. In the Mortgage Bankers Association’s Weekly Mortgage Applications Survey, released September 30 and covering the week ending September 25, total applications decreased 6.0% from the prior week. Purchase applications decreased 4%, and the unadjusted purchase index was 14% below the same week a year earlier. Refinance activity was hit particularly hard: down 9% for the week and 56% below the same week last year. MBA’s average contract rate on conforming 30-year loans increased to 7.30% from 7.12%, which MBA described as the sixth consecutive weekly increase and the highest rate since November 2023. Joel Kan, MBA’s Vice President and Deputy Chief Economist, said the jump in rates was “pushing borrowers to the sidelines.”
The listing side shows the same pressure. Realtor.com’s September 2026 Monthly Housing Trends Report, released September 30, found that 20.8% of active listings had a price reduction, the highest September reading since 2018 and the highest share in any single month since October 2022. Active listings increased 5.4% year over year to roughly 1.16 million, while pending listings were down 4.1%. The national median list price was $419,250, down 1.4% from a year earlier. Danielle Hale, chief economist at Realtor.com, said buyers are gaining leverage, “but higher mortgage rates are limiting how much of that opportunity they can use.”
Market snapshot
| Indicator | Latest reading | Comparison | Source and date |
|---|---|---|---|
| 30-year fixed rate | 7.28% | 7.03% the prior week; 6.34% a year earlier | Freddie Mac PMMS, Oct. 1, 2026 |
| 15-year fixed rate | 6.60% | 6.42% the prior week | Freddie Mac PMMS, Oct. 1, 2026 |
| Total mortgage applications | Down 6.0% | Week over week | MBA weekly survey, Sept. 30, 2026 (week ending Sept. 25) |
| Purchase applications | Down 4% | Week over week; unadjusted index 14% below the same week a year earlier | MBA weekly survey, Sept. 30, 2026 (week ending Sept. 25) |
| Refinance applications | Down 9% | Week over week; 56% below the same week a year earlier | MBA weekly survey, Sept. 30, 2026 (week ending Sept. 25) |
| MBA 30-year conforming contract rate | 7.30% | Up from 7.12%; sixth consecutive weekly increase; highest since November 2023 | MBA weekly survey, Sept. 30, 2026 (week ending Sept. 25) |
| Adjustable-rate share of applications | 10.3% | Increased from the prior week | MBA weekly survey, Sept. 30, 2026 (week ending Sept. 25) |
| Active listings with a price reduction | 20.8% | Highest September reading since 2018; highest single month since October 2022 | Realtor.com, Sept. 30, 2026 (September data) |
| Active listings | About 1.16 million | Up 5.4% year over year | Realtor.com, Sept. 30, 2026 (September data) |
| Pending listings | Down 4.1% | Year over year | Realtor.com, Sept. 30, 2026 (September data) |
| Median list price | $419,250 | Down 1.4% year over year | Realtor.com, Sept. 30, 2026 (September data) |
If you make your living originating mortgages or closing real-estate transactions, those numbers are not abstract statistics. They affect your pipeline and your income.
The idea behind this article
Your primary industry may be cyclical. Your client relationships don’t have to be.
What You Have Already Built
Mortgage loan officers and Realtors have already built capabilities that are valuable and hard to replicate:
- Client relationships
- Referral networks
- Financial conversations
- Lead generation
- Document collection
- Transaction management
- Follow-up
- Sales
- Trust
- Closing skills
So the question is a practical one. Why should those capabilities only generate revenue when somebody buys or refinances a house?
You Do Not Have to Leave the Mortgage or Real-Estate Industry
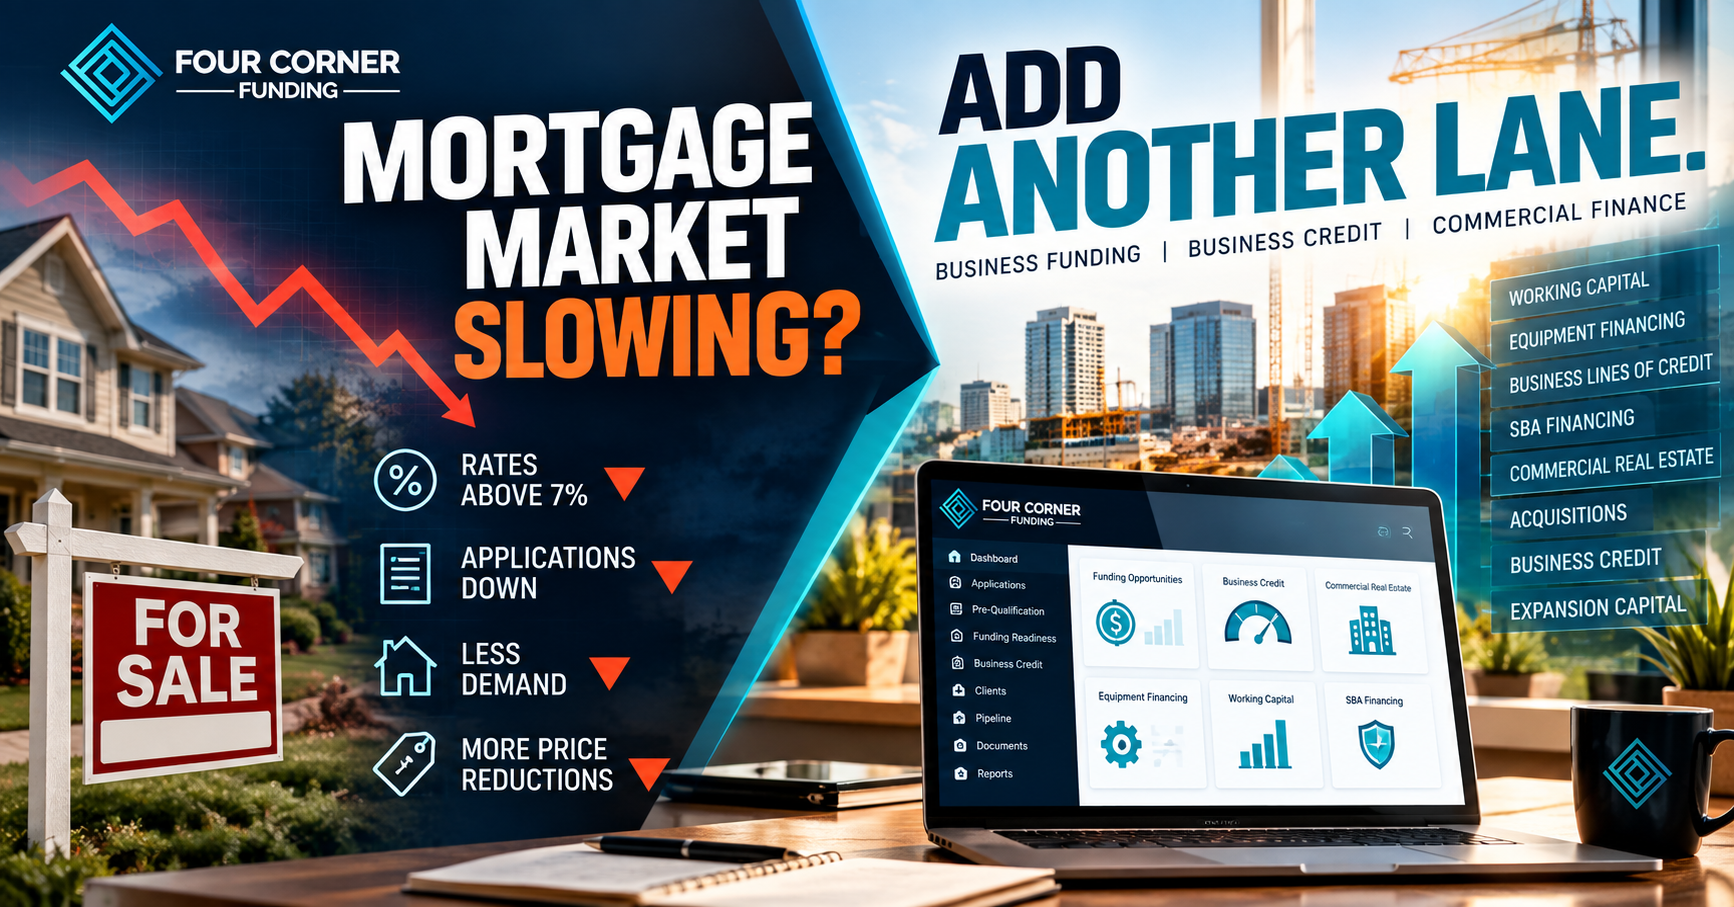
This is not an anti-mortgage article. Mortgage lending and real estate remain important businesses, and nothing in the data above says otherwise. The message is not “leave mortgage.” The message is “add another lane.”
Both industries are heavily affected by forces no individual professional controls:
- Rates
- Affordability
- Inventory
- Consumer confidence
- Housing cycles
A professional can remain fully active in mortgage or real estate while adding another category of financial services. Don’t replace the business you already have. Expand what it can offer.
You don’t have to abandon the business you built. You can make it capable of doing more.
Businesses Still Need Capital
Business owners continue to encounter capital needs across economic cycles, including when residential mortgage volume slows. The reasons are ordinary and recurring:
- Buying equipment
- Hiring
- Inventory
- Marketing
- Expansion
- Fulfilling contracts
- Acquiring competitors
- Purchasing buildings
- Managing uneven cash flow
- Opening locations
Those needs map to a range of financing and credit categories:
- Working capital
- Business lines of credit
- Term financing
- Equipment financing
- Revenue-based financing
- SBA financing
- Accounts receivable financing
- Acquisition financing
- Commercial real estate financing
- Construction financing
- Business credit
- Business credit card strategies
- Fundability and business credit building
Not every business qualifies for every product. Each request is subject to underwriting, documentation, and the funding source’s approval, which is why a structured way of assessing where a business stands matters as much as the product list.
Residential Mortgages Are One Part of the Capital Marketplace
MBA’s Quarterly Survey of Commercial/Multifamily Mortgage Bankers Originations, reported August 6, 2026, showed commercial and multifamily mortgage originations in the second quarter of 2026 running 16% higher than the second quarter of 2025 and 12% higher than the first quarter of 2026. Reggie Booker, MBA’s Associate Vice President of Commercial Research, said lending “maintained its upward trajectory,” while noting that activity “remains uneven across some capital sources and property sectors.” Separately, MBA’s Commercial/Multifamily Mortgage Debt Outstanding report put total debt outstanding at approximately $5.1 trillion at the end of the second quarter of 2026, an increase of $42.9 billion during the quarter.
Those figures do not mean every commercial finance sector is growing. They measure commercial and multifamily real estate lending, not business lending as a whole, and commercial finance has cycles of its own. The broader point is this: residential mortgages represent only one part of the capital marketplace, and many of the people you already know operate in the rest of it.
Loan officers and Realtors frequently know:
- Investors
- Contractors
- Builders
- Property managers
- Landlords
- Entrepreneurs
- Developers
- Business owners
Those same relationships may have commercial capital needs that never touch a residential closing.
Why Loan Officers Are Well Positioned
Mortgage loan officers may adapt particularly well to commercial finance. They already understand:
- Financial documentation
- Applications
- Borrowers
- Credit
- Debt
- Underwriting concepts
- Explaining financing
- Prospecting
- Follow-up
- Managing transactions
- Closing
A loan officer is not learning client-facing financial services from zero. They are learning another financing category, with its own documentation, underwriting models, and product rules.
For loan officers
You already know how to originate. The opportunity is to originate more than mortgages.
Why Realtors Are Well Positioned
Realtors regularly interact with people whose financial lives extend well beyond one property:
- Investors
- Contractors
- Landlords
- Entrepreneurs
- Developers
- Local business owners
- Buyers who own companies
- Sellers who own companies
A client’s financing needs may extend well beyond the residential transaction:
- Business working capital
- Equipment
- Commercial property
- Acquisition financing
- Business credit
- Expansion capital
Adding these capabilities can make a Realtor more valuable to the network they already built, and gives that network a reason to stay in touch between property transactions.
How Four Corner Funding’s White Label Model Works
Four Corner Funding White Label Partner Program
Your Brand. Your Clients. Your Platform.
Own Your Own Funding Company™
ACCESS CHANGES EVERYTHING™
A White Label Partner does not simply receive a referral link. The model is intended to let the partner build a business-funding and business-credit service line under their own brand, using Four Corner’s technology and infrastructure.
The client relationship remains central, and it remains yours. Clients work with your company, in your branded environment. See how the White Label Partner Program works.
The Platform and Infrastructure Behind It
Four Corner has built the operating infrastructure a funding company runs on, so a partner does not have to assemble it from separate tools. The platform may include:
Specific platform features may continue to evolve.
Adding Another Revenue-Producing Service Line
Adding commercial finance is a way to diversify. It gives a mortgage or real-estate business another revenue-producing service line, so that income is not dependent exclusively on residential closings.
White Label Partners can create additional revenue opportunities through eligible:
Compensation and program economics are governed by the executed partner agreement. Not every client qualifies, and no income or business result is guaranteed.
The Repeat Client Advantage
The biggest opportunity may not be the first transaction. Over the life of a company, a business owner might:
- Improve fundability
- Build business credit
- Pursue business credit cards
- Need working capital
- Finance equipment
- Purchase commercial real estate
- Acquire another company
- Return for additional capital
Not every client will follow that path, and many will need only one of those things.
Why the relationship matters
One business owner can have multiple capital needs throughout the life of the company.
That is why maintaining the relationship matters more than winning a single file.
Don’t Wait for Rates to Save Your Pipeline
Nobody can tell you where mortgage rates go next, and this article does not try. Mortgage professionals cannot control interest rates. Realtors cannot control national housing demand. What a professional can control is the number of services they are capable of providing to their own network.
What you can control
You cannot control the mortgage market. You can control how many ways your business is able to serve a client.
Keep originating mortgages.
Keep selling real estate.
Keep serving your market.
But when a business owner in your network needs capital, you do not necessarily have to send the opportunity somewhere else.
Own Your Own Funding Company™
Sources
- Freddie Mac, Primary Mortgage Market Survey, “Mortgage Rates Average 7.28%,” October 1, 2026.
- Mortgage Bankers Association, Weekly Mortgage Applications Survey, “Mortgage Applications Decrease in Latest MBA Weekly Survey,” September 30, 2026, covering the week ending September 25, 2026.
- Realtor.com, September 2026 Monthly Housing Trends Report, released September 30, 2026 (press release).
- Mortgage Bankers Association, Quarterly Survey of Commercial/Multifamily Mortgage Bankers Originations, “Commercial/Multifamily Borrowing Increased 16% in the Second Quarter of 2026,” August 6, 2026.
- Mortgage Bankers Association, Commercial/Multifamily Mortgage Debt Outstanding, second quarter of 2026.
Important information. Four Corner Funding is a brand of Four Corner Holdings, LLC. Four Corner Funding is not a lender. Financing is provided by independent third-party funding sources and is subject to underwriting, eligibility, documentation, geography, and approval. No financing result is guaranteed.
White Label Partner compensation and program terms are governed by the executed partner agreement. No income or business result is guaranteed.
Mortgage, real-estate, and other regulated professionals should verify that offering additional services complies with applicable licensing, employer, brokerage, and regulatory requirements.
Market data is presented as reported by each source on the dates shown and may be superseded by later releases. This article is general information, not legal, tax, or financial advice.