Before anyone at a funding source speaks with you, there is a good chance they have already looked your business up.
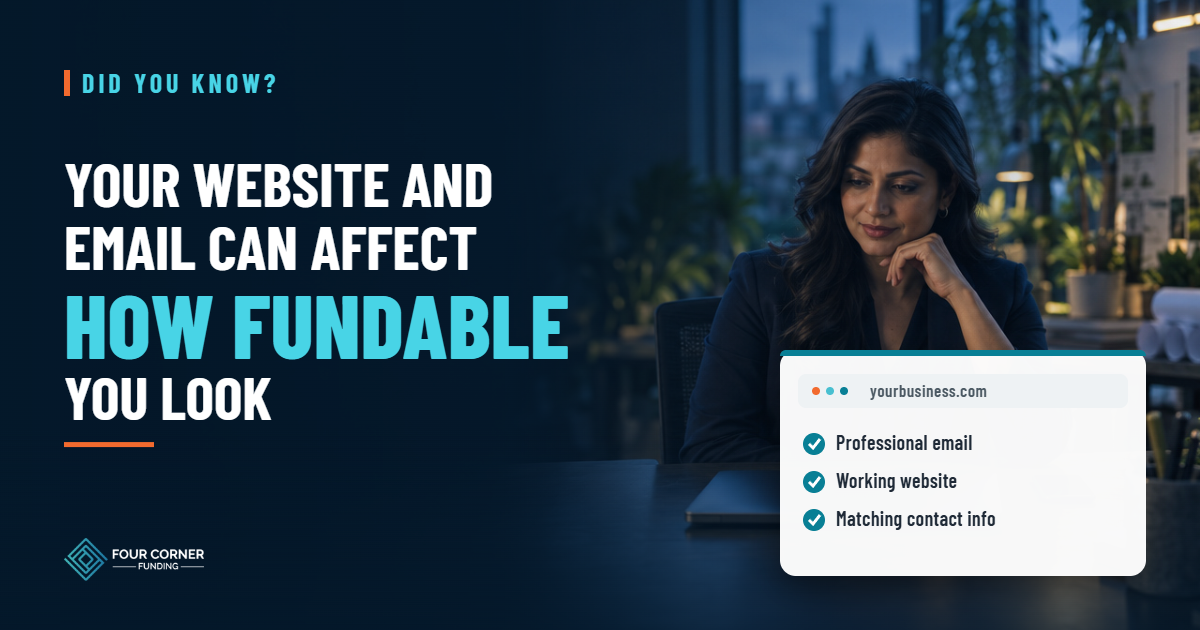
Did you know your business website and email can affect how fundable your company looks? Your online presence is often one of the first places a reviewer, card issuer, or verification system checks to confirm that a business is real, active, and the same business described in the application.
It is rarely the deciding factor. But it can either smooth the process or raise questions you did not expect.
Your Digital Presence Is Part of Verification
Funding sources need to confirm who they are dealing with. Alongside state records, tax records, and bank accounts, they may look at what the business shows the world: its website, its email address, its listed phone number, and how it describes what it does.
When those details are current and match the application, they support the file. When they are missing, outdated, or inconsistent, they can add friction. It is one more layer of the broader profile we described in what lenders may look at beyond your credit score.
Your digital presence can become part of the story your business tells before you ever speak to an underwriter.
What a Professional Presence Usually Includes
What This Does Not Mean
Not every funding source requires a website, and some businesses operate successfully without one. A polished site does not replace revenue, banking, or credit, and it will not overcome real weaknesses in the file.
You also do not need an expensive build. A simple, accurate, functioning site with correct contact information often does more for verification than an elaborate one that has gone out of date.
Details That Can Raise Questions
- A website address on the application that no longer loads, or a domain that has expired
- A free personal email used as the business contact
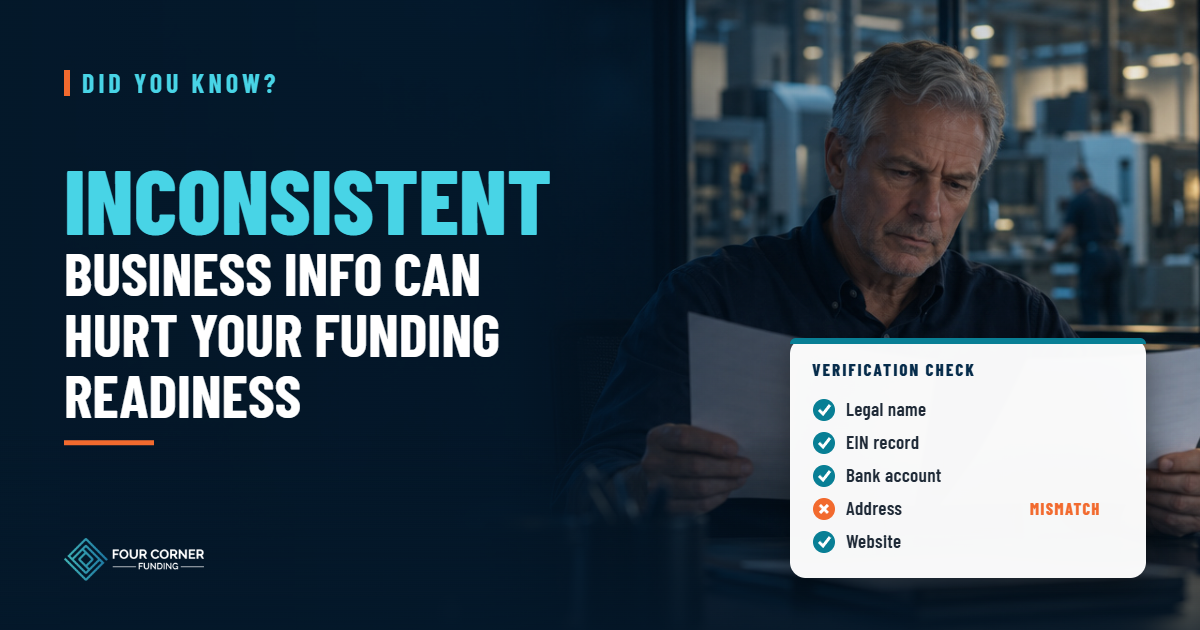
- An address or phone number online that differs from state and bank records
- A site that still says “coming soon” or “under construction”
- Services described online that do not match the industry on the application
- No working way to contact the business at all
None of these automatically leads to a decline. Each one can create a question a funding source has to resolve before moving forward.
A 30-Minute Self-Check
1. Search your business name the way a stranger would. Note everything that appears.
2. Open your website on a phone and a computer. Check that every page and contact link works.
3. Compare the name, address, and phone on the site with your state filing and bank account.
4. Confirm your domain and email renewals are current.
5. Update old directory listings so they match your current details.
The owner’s own profile matters too. For many small-business products, the owner’s personal credit is reviewed alongside the business, as we explained in how business and personal credit differ. A professional business presence helps the business side of that picture stand on its own.
Where Four Corner Funding Fits
Four Corner Funding’s Business Credit Builder begins with Tier 0, Foundation & Compliance, which covers the business information funding sources and bureaus may verify, including website, email, and phone where relevant. Pre-Qualification then looks at the full profile. You can begin without a credit check.
Funding if you’re ready. A path forward if you’re not.
Make a Strong First Impression.
See how your business profile looks from the outside, and what to tighten before you apply.
Your website will never be the reason a business gets funded. Making sure it supports the story instead of contradicting it is one of the easiest improvements an owner can make.
Disclaimer: This article is for general educational purposes only and is not credit, legal, tax, or financial advice. Four Corner Funding is not a lender and does not make credit decisions. Financing is provided by independent third-party funding sources and is subject to their underwriting, eligibility requirements, product availability, and documentation requirements, all of which vary. Not every funding source requires a website, and verification practices differ. Pre-Qualification and readiness results are not loan approvals or final credit decisions, and approval is not guaranteed.