Ask most business owners what a lender looks at and you will hear one answer: the credit score. It is the number people check before they apply, the number they worry about, and the number they assume decides the outcome.
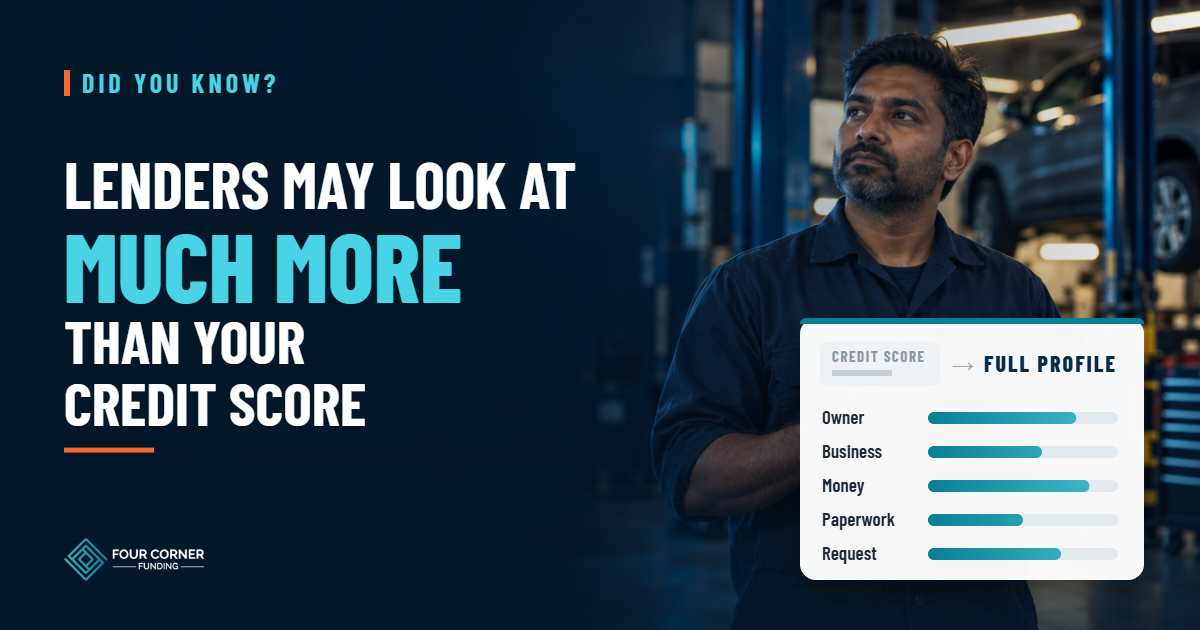
Credit matters. For many financing products it matters a great deal. But did you know lenders and other funding sources may look at much more than your credit score? In most business financing, the score is one input into a much larger picture of the owner, the business, and the request.
That larger picture is what we mean by fundability.
What a Credit Score Actually Summarizes
A personal credit score is a summary of one source of information: the owner’s personal credit file. It reflects how that person has handled credit, including payment history, balances, account age, and recent applications. It is useful, and it is fast to read.
What it does not show is the business. A score says nothing about whether deposits are steady, how much of each month’s revenue is already committed, whether the company has its own credit history, or whether the amount requested makes sense for the purpose. Those answers live elsewhere in the file.
We covered the first half of this idea in why a high personal credit score does not automatically make a business funding-ready. This article looks at the full profile a funding source may review.
Fundability Is a Profile, Not a Number
It helps to think of a funding file in five layers. Each one answers a different question, and a funding source may review some or all of them depending on the product.
The credit score sits inside the first layer. That is why two owners with the same score can receive very different answers: the other four layers can tell very different stories. Earlier articles in this series looked closely at business credit, credit utilization, and bank statements if you want to go deeper on any one of them.
Funding readiness is a profile, not a single number.
Why the Other Layers Matter
A funding source reviewing a business request is trying to answer a practical question: can this business support this obligation, for this purpose, over this period? A personal score speaks to how the owner has handled credit in the past. On its own, it cannot show whether the business generates enough cash to carry a new payment, whether that cash is already committed elsewhere, or whether the records support what the application says.
The other layers fill in what a score cannot see. When one layer is thin, a funding source may lean harder on the others, ask for more documentation, or point toward a different product.
Where the Emphasis Can Shift
Not every funding source weighs the five layers the same way, and the type of financing changes what tends to get the closest look. The examples below are general. They are not lender requirements, and criteria differ by funding source and transaction.
The practical takeaway: the same business can look stronger for one product than another. Knowing which layers a product tends to emphasize is part of choosing what to apply for.
It Cuts Both Ways
A strong score does not guarantee a strong file. An owner with excellent personal credit can still be held back by thin banking activity, heavy existing debt, missing documents, or a request that does not fit the product.
The reverse is also true. A score that is lower than you would like does not automatically mean no financing category exists. Depending on the product and the funding source, strength in other layers may matter. It is one more reason to understand the whole profile before deciding what is and is not possible.
Take a Quick Fundability Snapshot
For each layer, decide which column fits your business today. This is not a score, and it does not predict an outcome. It shows where to look first.
If you marked “Not sure” anywhere, start there. An unknown layer is harder to improve than a weak one, because you cannot fix what you have not seen.
Where Four Corner Funding Fits
Four Corner Funding’s Pre-Qualification is designed to look at the whole profile, not just the score: personal credit, business credit, revenue, banking, existing obligations, documentation, and the request itself.
If the business may be ready, the next step can be exploring appropriate financing through independent third-party funding sources. If it is not ready yet, the goal becomes identifying which layers need work and in what order. You can begin without a credit check.
Funding if you’re ready. A path forward if you’re not.
Your Score Is One Number. See the Whole Profile.
Find out how all five layers of your funding profile fit together, and what to work on first.
Your credit score is worth protecting. It is just not the whole story. The owners who are best prepared for capital are the ones who know what every layer of their file says before a funding source reads it.
Disclaimer: This article is for general educational purposes only and is not credit, legal, tax, or financial advice. Four Corner Funding is not a lender and does not make credit decisions. Financing is provided by independent third-party funding sources and is subject to their underwriting, eligibility requirements, product availability, and documentation requirements, all of which vary. The financing examples above are general and are not lender criteria. Pre-Qualification and readiness results are not loan approvals or final credit decisions, and approval is not guaranteed.