Many business owners assume that without a Social Security number, business credit cards are simply off the table. For some, that assumption keeps them from even asking.
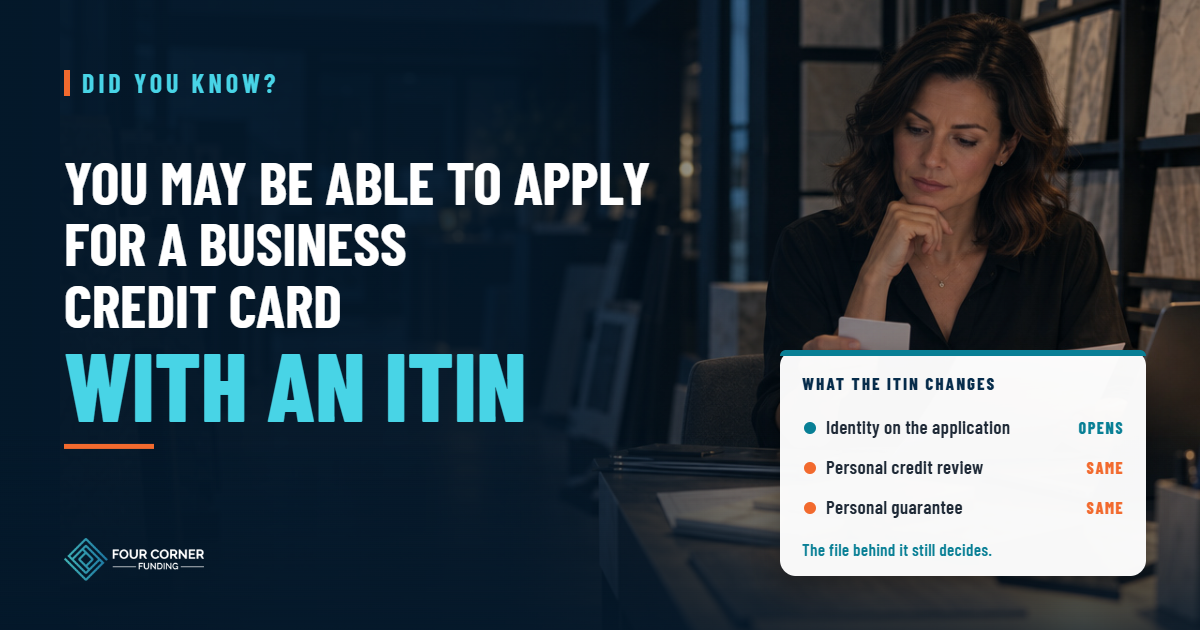
Did you know you may be able to apply for a business credit card with an ITIN? Some card issuers accept an Individual Taxpayer Identification Number in place of a Social Security number on business card applications. But the ITIN only answers one question: who is applying. Whether the application is approved still depends on the credit profile behind it.
What an ITIN Is, and What It Is Not
An ITIN is a nine-digit tax processing number issued by the IRS to individuals who need a U.S. taxpayer identification number but are not eligible for a Social Security number. It exists so people can file taxes and meet federal tax obligations.
An ITIN does not authorize work in the United States and does not change immigration status. It is also different from an EIN, which identifies the business rather than the owner. Many business owners with an ITIN have both: an ITIN for themselves and an EIN for their company.
An ITIN can open the application. The credit file behind it decides what happens next.
Acceptance Varies by Issuer, and It Changes
There is no single rule across the industry. Based on published reports, some major issuers accept ITINs on business card applications, others do not, and some have changed their policies over time. Even within one issuer, the experience can differ:
- Some applications accept an ITIN online, while others route ITIN applicants to a branch or a phone application.
- Additional identity documents may be requested before the application can move forward.
- Some application forms may not be set up to accept an ITIN even when the issuer’s policy allows it.
Because policies change, it is worth confirming directly with the issuer before applying, rather than relying on an older list.
What Actually Decides Approval
The personal guarantee still applies
Most small-business credit cards require the owner to personally guarantee the account. Applying with an ITIN changes how the issuer verifies identity. It does not remove personal responsibility for the debt.
The personal credit file still matters
Issuers typically review the owner’s personal credit. Many ITIN holders have a thin U.S. credit file, or none yet. A thin file can limit options regardless of which number is on the application.
The standard does not get looser
An ITIN does not create a separate, easier approval track. Expect the same review of payment history, utilization, and depth as any other applicant.
We covered why the owner’s credit stays in the picture in how business credit and personal credit differ, and why depth and history matter in why the age of your credit accounts can matter.
Other Paths Owners Sometimes Consider
Cash-flow-based business cards. Some business card products are underwritten mainly on the company’s bank balances and cash flow, and some do not require a personal guarantee. These generally suit established businesses with meaningful cash on hand, not startups.
Building the personal file first. Owners with little U.S. credit history sometimes start with products designed for building credit, then move to business cards once a track record exists.
A caution on workarounds. One suggestion that circulates is to have a partner apply as the primary cardholder and add you as an employee card. That places the liability on the partner and builds little or nothing for you. It is not a substitute for building your own profile.
Practical Steps Before You Apply
- Confirm your ITIN is active. ITINs can expire if they are not used on a federal tax return for a period of time. Check your status with the IRS.
- Know your credit file. Find out whether a U.S. credit file exists under your ITIN and what it shows.
- Get the business foundation in order. An EIN, a business bank account, and consistent business records support the business side of the application.
- Have identity documents ready. Some issuers ask for additional verification from ITIN applicants.
- Confirm the issuer’s current policy. Ask before you apply, and ask how the application must be submitted.
- Apply with a plan. Scattered applications add inquiries without strengthening the file, as we covered in how business credit cards fit into a larger capital strategy.
Where Four Corner Funding Fits
Business owners applying with an ITIN may qualify for select business credit products; additional identity verification may be required. Four Corner Funding helps owners understand where their personal and business credit profiles stand, build the business foundation through the Business Credit Builder, and plan which products to pursue and in what order. Pre-Qualification is a starting point, and you can begin without a credit check.
Funding if you’re ready. A path forward if you’re not.
Know Where You Stand Before You Apply.
See how your credit profile may read and which business credit products may fit.
Not having a Social Security number does not have to mean no business credit. It does mean the credit file, the business foundation, and the plan matter just as much as they do for anyone else.
Disclaimer: This article is for general educational purposes only and is not credit, legal, tax, immigration, or financial advice. Four Corner Funding is not a lender or card issuer and does not make credit decisions. Card issuers set their own identification, underwriting, and eligibility requirements, which vary and may change; acceptance of an ITIN is not guaranteed. Financing is provided by independent third-party funding sources and is subject to their underwriting, eligibility requirements, product availability, and documentation requirements, all of which vary. Consult the IRS or a qualified tax professional regarding ITIN status. Pre-Qualification and readiness results are not loan approvals or final credit decisions, and approval is not guaranteed.