Your credit score looks fine. Maybe even good. So when a funding source hesitates, it can feel like the answer does not match the number.
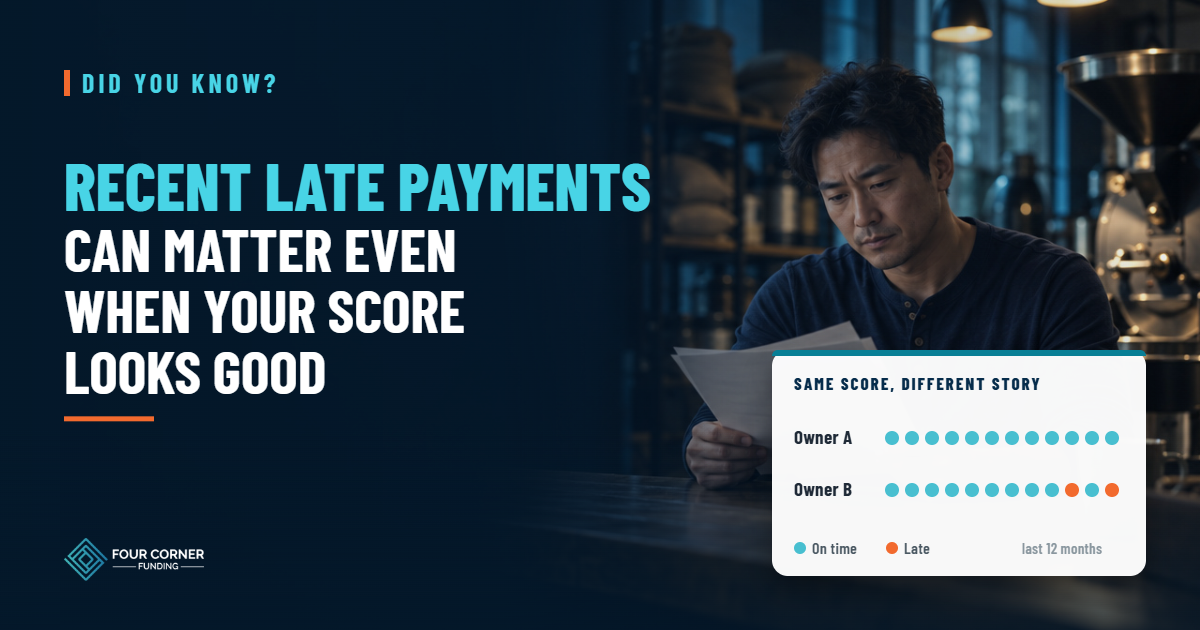
Did you know recent late payments can matter even when your credit score looks good? A score is a summary. The credit report behind it holds the details, and a funding source reviewing that report may look closely at what happened recently, not just where the score landed.
Understanding the difference between the number and the history behind it can help you see your file the way a reviewer might.
What a Score Can Hide
A credit score compresses a lot of information into a single figure: payment history, balances, account age, recent applications, and more. A long, healthy history can cushion the score impact of a single recent problem. The number may barely move.
The report, though, still shows the late payment, the account it was on, and when it happened. Many funding sources review the report itself, not just the score, especially for business financing where the owner’s personal credit is part of the picture. We covered why that is in how business credit and personal credit differ.
Recency, Frequency, and Severity
When late payments appear, three questions tend to shape how they read:
Recency
How long ago did it happen? A late payment from last month can raise different questions than one from several years ago.
Frequency
Was it a one-time event or part of a pattern? Several late payments across different accounts can tell a different story than a single slip.
Severity
How late was it? A payment reported 30 days late is generally viewed differently from one that went much further, or ended in collections or a charge-off.
The type of account can matter too. A late housing or business-related payment may draw more attention from some reviewers than others. Different funding sources evaluate derogatory information differently, and there is no single rule that applies everywhere.
Two people can have similar scores and very different credit profiles.
Same Score, Different Story
Consider two business owners whose scores fall in roughly the same range. The example is illustrative, not a lender rule.
On paper the scores look alike. To a funding source reading the full report, the two files may say very different things about what is happening right now.
Why Recent History Gets Attention
A funding source is trying to judge how an obligation is likely to be handled going forward. Recent late payments can suggest current cash pressure, even if the long-term history is strong. That is why the most recent months of a credit file can carry more weight than their share of the total history.
How much it matters depends on the product. Some financing leans heavily on the owner’s credit; other products put more emphasis on revenue, banking, collateral, or invoices. We explained that range in what lenders may look at beyond your credit score.
If You Have a Recent Late Payment
- Bring the account current and keep it there. Every on-time month after the event adds positive history.
- Review your reports. Look at all three consumer credit reports so you know exactly what a reviewer will see.
- Check for errors. If something is reported inaccurately, you can dispute it through the credit bureau’s process. Accurate information generally stays on the report for a set period, so the focus there is building new positive history.
- Prevent a repeat. Automatic payments or reminders on every account can stop a small oversight from becoming a pattern.
- Be ready to explain. If a funding source asks, a clear, factual explanation of what happened and what changed can help put a one-time event in context.
Timing Your Next Application
Sometimes the strongest move is not to apply immediately. Building a stretch of clean, on-time history after a recent late payment can change how the file reads. Applying repeatedly in the meantime usually does not help, as we covered in why more funding applications are not always the answer.
The right timing depends on the product, the funding source, and the rest of the profile. There is no universal waiting period.
Where Four Corner Funding Fits
Four Corner Funding’s Pre-Qualification looks at the profile behind the score, along with business credit, revenue, banking, and the request itself. If the business may be ready, the next step can be exploring options through independent third-party funding sources. If recent history needs time or attention first, the plan can start there. You can begin without a credit check.
Funding if you’re ready. A path forward if you’re not.
See What’s Behind the Number.
Understand how your full credit profile may read, and what to work on before your next request.
A good score is worth protecting. So is the history underneath it. The owners who are best prepared for funding know what their report says, not just what their score says.
Disclaimer: This article is for general educational purposes only and is not credit, legal, tax, or financial advice. Four Corner Funding is not a lender or a credit repair organization and does not make credit decisions. Financing is provided by independent third-party funding sources and is subject to their underwriting, eligibility requirements, product availability, and documentation requirements, all of which vary. The example above is illustrative and not lender criteria. Credit reporting timeframes and dispute processes are governed by applicable law and bureau procedures. Pre-Qualification and readiness results are not loan approvals or final credit decisions, and approval is not guaranteed.